Royal Decree-Law 32/2021: The labour reform in Spain
With the entry into force of Royal Decree-Law 32/2021 on 31 December 2021, all contracts in Spain are open-ended, and the conclusion of contracts for specific work or services disappears.
With the entry into force of Royal Decree-Law 32/2021 on 31 December 2021, all contracts in Spain are open-ended, and the conclusion of contracts for specific work or services disappears.
The Royal Decree-Law 26/2021 incorporates new rules to address the treatment of the Capital Gains Tax in Spain (IIVTNU). Article 104.5 of the Law Regulating Local Tax Office, which includes a new condition to not being subject to the tax, and Article 107 (which establishes two new calculation methods for the tax base of the Capital Gains Tax, in the case of capital gain) stand out.
Collective agreements may establish additional formal requirements to formalize a disciplinary dismissal. Their non-compliance may result in administrative sanctions for the company.
The real estate lease-purchase contract allows the rental of a property for a specific period and grants the tenant the right to buy it at a pre-determined price at the end of said period.
Spanish bankruptcy regulations list the conducts that determine the liability of the directors in bankruptcy proceedings. The consequences of such behaviour include disqualification, loss of rights associated with the position of a creditor of a bankruptcy or a sentence to cover the insolvency deficit.
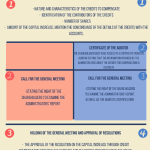
The capital increase through credit compensation reduces the risk of insolvency and avoids the declaration of insolvency proceedings, thus providing a solution for companies with high liabilities.
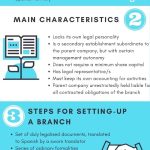
A branch is a secondary establishment subordinate to its parent company, meaning that it is an extension of the parent company in Spanish territory and does not require a minimum share capital for its incorporation.
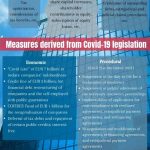
Spain provides companies with a range of economic, labour, contractual, corporate, procedural and fiscal measures. The Covid-19 legislation complements them with new economic and procedural measures to prevent corporate insolvency.
On the 23rd September took place the Iberian Lawyer’s 2021 Forty under 40 Awards that recognized Alberto Álvarez as the Lawyer of the Year Energy.
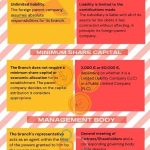
Opening a branch in Spain does not require a minimum share capital. Opening a subsidiary, on the contrary, requires a minimum share capital of €3.000 for Limited Liability Companies (LLC) or €60.000 for Public Limited Company (PLC).
© 2026 Mariscal Abogados, S.L.P.
Legal NoticePrivacy PolicyCookies Policy